
The Long-Term Care Landscape: Trends, Costs, and Planning Realities
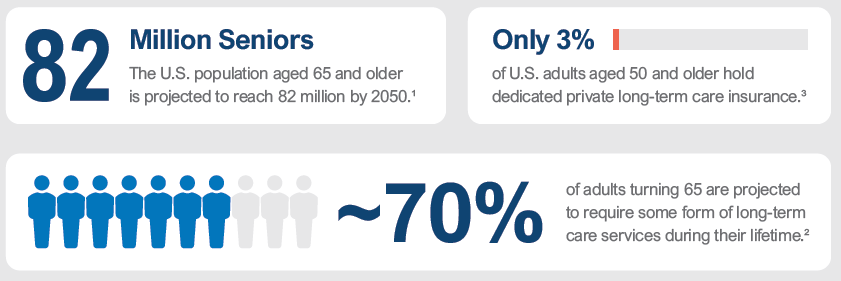
As Americans experience longer lifespans, the demand for long-term care services continues to increase alongside the cost of care. Because many adults remain uninsured, unmanaged care needs can place significant emotional and financial demands on families.
Explore the data below to understand why a dedicated long-term care strategy is an important component of a comprehensive financial plan.
The Growing Need for Care
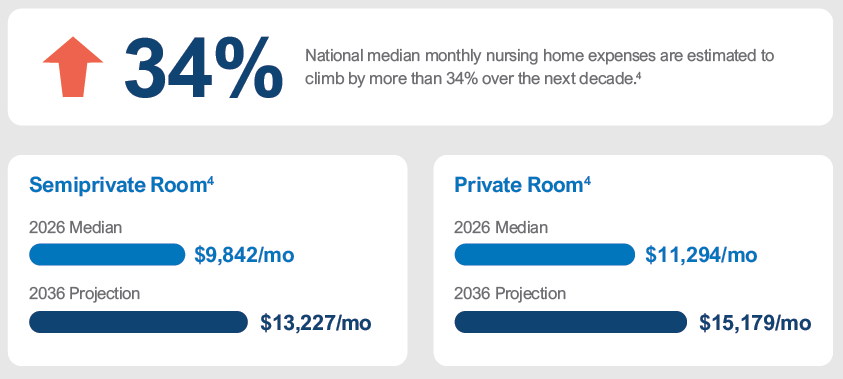
Projected Rising Costs of Care
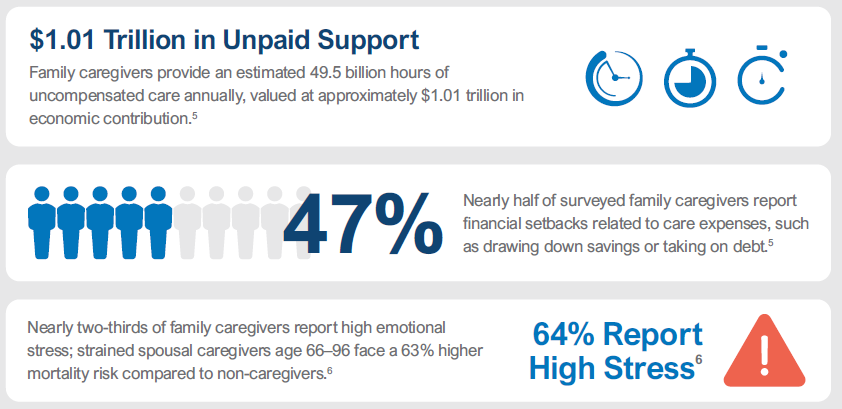
The Toll on Families and Caregivers
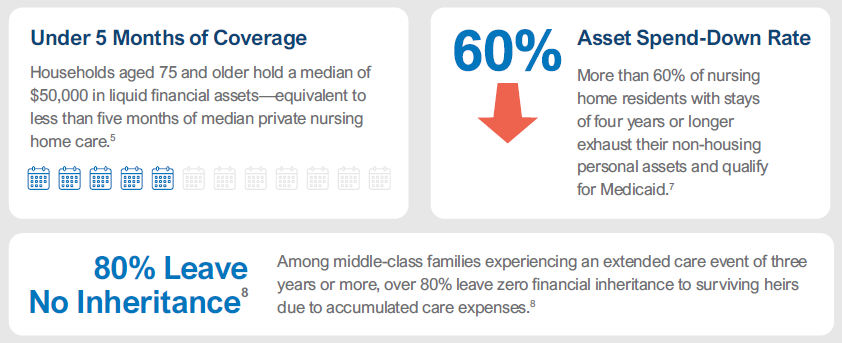
Considerations for Retirement Portfolios
This material is provided for educational and informational purposes only and should not be construed as specific legal, tax, or investment advice. Individuals must consult with their independent tax professional, legal counsel, or financial professional regarding their personal situation. Asset-based long-term care products are insurance policies (life insurance or annuities) with long-term care riders. Products and riders contain exclusions, limitations, waiting periods, and terms for keeping them in force, and are subject to state availability and medical underwriting. Surrender charges may apply to early withdrawals. Guarantees are backed solely by the financial strength and claims-paying ability of the issuing insurance company. Projections are illustrative and based on mathematical assumptions that may not reflect actual future economic conditions. Not a deposit. Not FDIC-insured. May go down in value. Not insured by any federal government agency. Not guaranteed by any bank or savings association.
– – – – – – – – – – – – – – – – – – – – – – – – –
Sources
- U.S. Census Bureau (2023)
- U.S. Senate Special Committee on Aging / HHS (2025)
- Kaiser Family Foundation (2023)
- SeniorLiving.org (2026 Projections)
- AARP Public Policy Institute (2026)
- AARP / National Alliance for Caregiving (2025)
- JAMA Network Open (2025)
- Center for Retirement Research at Boston College (2023)